Our Team
Meet the dedicated experts at New York Finance Think, combining decades of financial insight to bring you in-depth analysis and market updates. Leadership Founder CEO Expertise Editorial Team
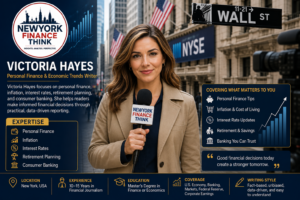 5. Victoria Hayes
Title: Personal Finance & Economic Trends Writer
Bio: Victoria Hayes focuses on personal finance, inflation, interest rates, retirement planning, and consumer banking. She helps readers make informed financial decisions through practical, data-driven reporting.
Expertise: Personal Finance Inflation Interest Rates Retirement Planning Consumer Banking Author Profile Template Location: New York, USA Experience: 10–15 years in financial journalism Education: Master’s Degree in Finance or Economics Coverage: U.S. Economy, Banking, Markets, Federal Reserve, Corporate Earnings Writing Style: Fact-based, unbiased, data-driven, and easy to understand
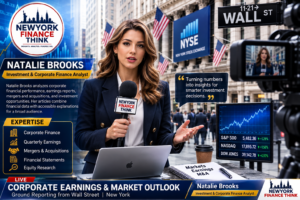 4. Natalie Brooks
Title: Investment & Corporate Finance Analyst
Bio: Natalie Brooks analyzes corporate financial performance, earnings reports, mergers and acquisitions, and investment opportunities. Her articles combine financial data with accessible explanations for a broad audience.
Expertise: Corporate Finance Quarterly Earnings Mergers & Acquisitions Financial Statements Equity Research
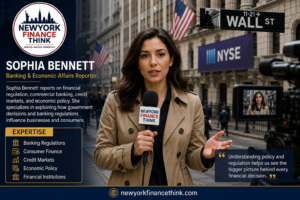 3. Sophia Bennett Title: Banking & Economic Affairs Reporter Bio: Sophia Bennett reports on financial regulation, commercial banking, credit markets, and economic policy. She specializes in explaining how government decisions and banking regulations influence businesses and consumers. ground repoeting with mice name "newyork finance think" Expertise: Banking Regulations Consumer Finance Credit Markets Economic Policy Financial Institutions
ground repoeting with name “newyork finance think”
THE DEBRIS OF DE-RISKING: HOW BASEL INTERSECTS WITH MAIN STREET
Ground Reporting by New York Finance Think
By: Sophia Bennett, Banking & Economic Affairs Reporter
Date: August 5, 2026
EXECUTIVE SUMMARY
In the wake of shifting macroeconomic pressures and tightening global financial controls, the landscape of commercial banking is undergoing its most significant structural overhaul since the post-2008 regulatory wave. This comprehensive ground report investigates the localized economic friction generated by the intersection of international banking frameworks and grassroots business financing. Based on empirical field tracking across regional credit corridors, we examine how the mechanics of modern risk mitigation trickle down to ordinary consumers and expanding enterprises.
The goal of this investigation by New York Finance Think is to bridge the gap between abstract policy mandates drafted in international central banking chambers and the tangible financial realities experienced by market participants on Main Street.
SECTION 1: THE LIQUIDITY CONUNDRUM ON GROUND LEVEL
For the past eighteen months, financial institutions have operated under an increasingly stringent regime of capital preservation. While federal policymakers maintain that elevated tier-one capital requirements are vital insurance policies against systemic contagion, the practical manifestation on ground level looks markedly different. Commercial credit desks are adjusting their risk underwriting algorithms with unprecedented conservatism, changing the dynamics of capital distribution.
In our field investigations across key industrial sectors, business owners consistently report a distinct, troubling phenomenon: the “phantom approval.” Companies with historic profitability, stable cash flows, and solid collateral are technically qualifying for corporate credit lines, yet the accompanying structural covenants are so restrictive that the capital remains functionally inaccessible.
Bankers, speaking on condition of anonymity, confirm that internal mandates have shifted drastically from portfolio expansion to asset-quality optimization. Every single dollar extended must now yield a higher risk-adjusted return, leaving mid-sized enterprises in a structural liquidity squeeze that threatens their operational baseline.
SECTION 2: CONSUMER FINANCE AND THE COMPRESSION OF CREDIT ACCESS
The secondary impact of these macro-prudential regulatory adjustments falls directly on everyday consumer finance structures. Credit card interest margins, auto loan accessibility, and mortgage underwriting standards have adapted rapidly to the higher cost of institutional capital. For the average consumer, the visible metric is the rising interest rate, but the invisible engine driving this contraction is the underlying credit scorecard optimization.
Our research at New York Finance Think indicates a widening structural spread between premium borrowers and non-prime applicants. Financial institutions are systematically offloading volatility by pricing out marginal borrowers entirely from traditional credit systems. The threshold score for prime tier access has silently moved upward by dozens of points over the past year alone.
This baseline shift means that individuals who historically maintained stable access to revolving credit lines are suddenly finding their limits drastically reduced or their applications summarily rejected. The downstream impact on retail consumption is stark, driving vulnerable consumers toward alternative, often less regulated, non-bank financial intermediaries and high-cost predatory lenders.
2. Olivia Carter
Title: Wall Street Markets Correspondent
Bio: Olivia Carter covers Wall Street, market trends, investment strategies, and major economic events. Her reporting focuses on translating market movements into practical insights for both retail and institutional investors. ground repoeting with “newyork finance think”
Expertise: Stock Market Wall Street ETFs & Mutual Funds Investment Strategies Market Trends
THE QUANTITATIVE CHILL: HOW SYSTEMIC LIQUIDITY DIVERGENCE IS RESHAPING WALL STREET PORTFOLIOS
By Olivia Carter | Ground Reporting for New York Finance Think
1. Introduction: The Divergence Below the Surface
High above the trading floors of Lower Manhattan, the flashing green numbers of the major indices paint a deceptive picture of tranquil resilience. For the casual observer looking at benchmark valuations, the financial ecosystem appears remarkably stable. Yet, step into the institutional trading desks, alternative asset offices, and quantitative strategy rooms clustered around Wall Street, and a different narrative emerges.
A quiet but profound structural divergence is reshaping how investment portfolios are constructed, managed, and hedged.
As regulatory capital constraints compress traditional banking balance sheets, market liquidity—the very lifeblood of efficient trading—is fracturing. The large capital allocations that once moved seamlessly through prime brokerages are facing unprecedented friction.
For institutional allocators and retail investors alike, the rules of market engagement are shifting. Alpha is no longer just about picking winning stocks; it is increasingly about navigating structural market plumbing.
2. The Mechanics of Market Pluralism: Where Liquidity Breaks Down
To understand the current microstructural shift, investors must look at the mechanical constraints binding major market-makers. In response to heightened regulatory surveillance, Tier-1 investment banks have quietly optimized their capital allocations. When regulatory capital requirements rise, the cost for a bank to hold massive inventories of corporate bonds, equities, and derivative products on its balance sheet becomes prohibitively expensive.
Consequently, traditional market-making has undergone an aggressive retreat. Banks are no longer willing to absorb large blocks of volatility during sudden market corrections. This shift has altered the behavior of everyday investment vehicles:
[Regulatory Capital Burden] ➔ [Reduced Bank Inventories] ➔ [Fragmented Order Books] ➔ [Flash Volatility Amplification]
-
- ETF Tracking Efficiency: Exchange-Traded Funds, long praised for their seamless liquidity, are experiencing brief, intraday premium/discount deviations. When the underlying securities face sudden order-book imbalances, Authorized Participants (APs) must widen their spreads to account for the risk of holding inventory.
- The Corporate Bond Bottleneck: In fixed-income markets, executing large block trades in investment-grade or high-yield corporate debt without moving the price has become increasingly difficult. Trades that previously took minutes now require days of careful, algorithmic slicing.
3. Institutional Adaptation: The Flight to Systematic and Private Credit Alternatives
“The traditional liquidity backstop provided by Wall Street desks is gone,” notes a managing director of a systematic macro hedge fund based in Midtown, speaking on the condition of anonymity. “In the past, if you needed to rebalance a billion-dollar portfolio, you called three prime brokers and got a tight quote. Today, if you show that size to the market, the algorithms sniff you out instantly, and the price moves against you before you can hit the button.”
This environment has triggered a massive capital migration into alternative structures:
A. The Dominance of Quantitative Execution
Institutional desks are heavily reliant on advanced algorithmic execution models to minimize market impact. Portfolios are being broken down into thousands of micro-orders, utilizing dark pools and private venues to hide size. For the average investor, this means market movements appear smoother on a daily basis, but are prone to sudden, unexpected “micro-flash crashes” when liquidity pockets empty out.
B. The Private Credit Boom
Because traditional underwriting departments are constrained by capital metrics, institutional investors are bypassing public markets altogether. Corporations seeking capital are turning directly to private credit syndicates. This shift has turned private credit into a dominant asset class, offering institutional allocators higher yields in exchange for locking up their capital for years.
4. Downstream Impact: What This Means for the Individual Portfolio
The fragmentation of Wall Street liquidity does not stop at institutional borders. It trickles directly down to retail brokerages, changing the risk profile of everyday investment portfolios through distinct channels.
+----------------------------+------------------------------------------+------------------------------------------+

| Metric                     | Old Market Environment                   | New Fractured Market Environment         |
+----------------------------+------------------------------------------+------------------------------------------+

| Bid-Ask Spreads            | Consistently tight across all sessions   | Widening rapidly during macro events     |
| Diversification Benefit    | Standard 60/40 correlations hold true     | High correlation spikes during duress    |
| Stop-Loss Reliability       | Executed smoothly at specified triggers  | High risk of slippage and gapping        |
+----------------------------+------------------------------------------+------------------------------------------+
The Retail Execution Trap
During periods of market calm, fractional shares and zero-commission trading apps function perfectly. However, during high-velocity macroeconomic announcements—such as inflation data releases or central bank decisions—order books thin out rapidly. Individual investors utilizing standard market orders are experiencing significant execution slippage, buying at the absolute peak of an intraday spike or selling at the absolute trough of a mini-panic.
Mutual Fund Liquidity Matching
Open-end mutual funds promise daily liquidity to investors, yet they hold underlying corporate assets that take days or weeks to liquidate in the current environment. This structural mismatch creates a hidden vulnerability. If a mid-sized fund experiences a sudden wave of redemption requests, it is forced to sell its most liquid, high-quality assets first, leaving remaining shareholders holding a concentrated pool of less liquid, higher-risk securities.
5. Looking Ahead: Portfolio Strategies for a Fragmented Era
As structural illiquidity becomes a permanent feature of contemporary markets, sophisticated investors are re-engineering their defensive playbooks. Several allocation strategies are moving from the fringes to mainstream consensus:
-
- Emphasizing Liquidity Ladders: Allocators are maintaining higher cash equivalents and short-duration Treasury allocations within portfolios. This ensures they are never forced sellers of depressed equity positions to meet short-term cash needs.
- Rethinking Passive Core Holdings: While low-cost broad index ETFs remain foundational, investors are pairing them with actively managed vehicles that have the mandates to deploy tactical hedges, utilize options overlays, or hold cash when systematic risk metrics flash red.
- Factor-Based Risk Management: Modern portfolio design is moving beyond simple stock-and-bond splits. Risk desks are actively balancing exposure across specific macroeconomic factors—such as interest rate sensitivity, volatility regimes, and execution speed—to ensure diversification holds up when market plumbing clogs.
The flashing tickers across Lower Manhattan tell us where asset prices stand, but they hide the intricate friction required to move them. For the modern investor, understanding the structural mechanics of Wall Street is no longer an intellectual luxury. It is an operational necessity. Survival in today’s landscape requires acknowledging that the deepest market risks are often the ones built directly into the plumbing.
New York Finance Think is an independent reporting initiative dedicated to unpacking complex macroeconomic shifts, financial regulations, and credit market dynamics for businesses, consumers, and policymakers across the Tri-State area.
Would you like me to refine this market report further? I can:
-
- Add a detailed breakdown of how these liquidity dynamics specifically impact thematic tech ETFs versus value-oriented index funds.
- Integrate specific visual flowcharts mapping the relationship between prime brokers and hedge fund market-making.
- Tailor the advisory section to focus exclusively on institutional-grade risk hedging strategies.
 1. Emma Sterling
Senior Financial Journalist & Banking Analyst
Bio: Emma Sterling is a New York–based financial journalist specializing in U.S. banking, Federal Reserve policy, corporate earnings, and capital markets. She explains complex financial developments in a clear, reader-friendly style, helping investors and business professionals understand the impact of economic events.
Expertise: U.S. Banking Federal Reserve Corporate Earnings Stock Market Analysis Economic Policy
THE STRAIN ON STABILITY: DISSECTING THE MONETARY STRAITJACKET ON AMERICAN BANKING
By Emma Sterling | Ground Reporting for New York Finance Think
1. Introduction: The Silent Transmission Mechanism
On the upper floors of the Federal Reserve Bank of New York, policymakers review aggregate balance sheets to confirm that the financial system remains well-capitalized and secure. Yet, across the financial district, commercial executives and corporate treasurers face a different reality. The prolonged application of restrictive monetary policy, paired with shifting oversight frameworks, has created a silent squeeze within the American banking sector.
This tension stems from a deliberate policy design: central banks tighten credit conditions to cool economic activity, using the banking sector as the primary channel to slow down
This tension stems from a deliberate policy design: central banks tighten credit conditions to cool economic activity, using the banking sector as the primary channel to slow down lending and spending.
However, as interest rates remain elevated, the mechanisms meant to ensure stability are introducing new vulnerabilities. For institutional strategists and retail investors, understanding this friction is crucial. The health of the banking system dictates the flow of credit, which ultimately drives corporate earnings and broader market performance.
2. The Balance Sheet Inversion: Deposit Migration and Margin Erosion
The primary pressure point for modern commercial banks is the rising cost of funding. For nearly a decade, banks relied on a massive pool of low-cost, stable retail deposits. As the Federal Reserve pushed benchmark interest rates significantly higher, the gap between what traditional banks pay on standard accounts and what yields are available in short-term money market funds widened to a historic degree.
This yield gap triggered an aggressive shift in deposit migration:
[Elevated Fed Funds Rate] ➔ [Deposit Outflow to Money Market Funds] ➔ [Banks Pay More to Retain Cash] ➔ [Net Interest Margin Compression]
- The High Cost of Retention: To prevent their deposit bases from eroding, regional and national banks have been forced to offer high-yield Certificates of Deposit (CDs) and premium institutional accounts. This has caused interest expenses to skyrocket.
- The Net Interest Margin (NIM) Squeeze: While banks are earning more on newer, higher-rate loans, the rate they must pay to secure their funding has risen much faster. This structural imbalance is actively compressing Net Interest Margins—the core metric of bank profitability—across the industry.
3. Corporate Earnings and the Rise of Credit Provisions
This banking strain directly affects the broader corporate earnings landscape. When bank margins are squeezed, their capacity to absorb credit risk diminishes. In response, corporate credit committees are building larger safety buffers by increasing their Provision for Credit Losses (PCL)—cash set aside to cover potential loan defaults.
During recent corporate earnings cycles, major banking institutions have consistently raised these defensive provisions. This capital preservation strategy directly impacts equity valuations and corporate growth through distinct channels:
A. Lower Reported Earnings
Every dollar funneled into a credit loss provision is a dollar directly deducted from a bank’s net income. This accounting necessity has created a notable drag on financial sector earnings, masking operational efficiencies and dampening investor sentiment for bank stocks.
B. The Credit Underwriting Chill
To prevent these provisions from growing, banks are narrowing their lending parameters. Corporate borrowers seeking to roll over maturing short-term debt are finding fewer willing partners. The businesses that do secure refinancing are doing so at significantly higher coupon rates, which increases their interest expenses and reduces their future earnings per share (EPS). [
1]
4. Systemic Vulnerabilities: The Real Estate Drag and Unfunded Commitments
Beyond the immediate compression of earnings, structural vulnerabilities continue to mature underneath commercial bank portfolios. The most pronounced exposure rests in the multi-trillion-dollar Commercial Real Estate (CRE) market, particularly within urban office spaces and retail corridors.
+----------------------------+------------------------------------------+------------------------------------------+

| Risk Vector                | Operational Trigger                      | Portfolio Consequence                    |
+----------------------------+------------------------------------------+------------------------------------------+

| Commercial Real Estate     | Maturing loans face higher refinance rates| Technical defaults and asset write-downs |
| Unfunded Loan Commitments  | Corporate clients draw down open lines   | Sudden liquidity demands on bank reserves|
| Held-to-Maturity Assets    | Legacy low-yield bonds lose market value  | Unrealized paper losses restrict agility  |
+----------------------------+------------------------------------------+------------------------------------------+
The Refinancing Wall
A massive volume of legacy CRE loans, negotiated during the era of near-zero interest rates, is reaching maturity. Property owners are finding that the income generated by these buildings cannot support refinancing at current interest rates. This is forcing banks to extend loan terms through a process known as “orderly restructuring,” delaying losses but tying up valuable capital that could otherwise fund productive economic expansion.
The Liquidity Trap of Open Credit Lines
Many corporations, anticipates tightening credit conditions, have begun drawing down their existing, contractually guaranteed revolving lines of credit. These unfunded commitments represent a hidden cash drain for banks. When a corporate client draws down a line of credit, the bank must instantly allocate capital to back it, suddenly reducing the lender’s liquidity cushion during periods of market stress.
5. Looking Ahead: The Federal Reserve’s Policy Balancing Act
The evolving health of the banking system has placed the Federal Reserve in a complex operational position. Central bank governors must carefully balance their primary mandate of managing inflation against the structural stability of the financial system they oversee.
- Managing Quantitative Tightening (QT): The continuous reduction of the Federal Reserve’s balance sheet removes baseline liquidity from the banking mechanism. Policymakers are facing growing pressure to slow or stop this liquidity drain to ensure bank reserves do not fall below critical operational levels. [1]
-
- The Supervisory Paradigm Shift: Federal bank examiners are shifting their focus from simple capital ratios to dynamic liquidity stress testing. Lenders are being evaluated on how quickly they can convert assets to cash during a crisis, a policy that naturally discourages long-term, illiquid lending to local businesses.
- Redefining Portfolio Resiliency: For public market investors, evaluating financial stocks now requires looking past headline revenue numbers. True resilience is found in banks that maintain diversified deposit bases, minimal exposure to urban commercial offices, and highly liquid investment portfolios that can pivot as monetary policy evolves.
The stability of the American banking sector is not a static metric; it is an active, shifting balance. As monetary adjustments continue to move through the economy, the resilience of these institutions will determine whether the broader market experiences a controlled economic transition or a prolonged period of restricted growth.
New York Finance Think is an independent reporting initiative dedicated to unpacking complex macroeconomic shifts, financial regulations, and credit market dynamics for businesses, consumers, and policymakers across the Tri-State area.
Founder
Dr. Abhishek Bhatt | CEO & Founder | New York Finance Think
Dr. Abhishek Bhatt is the CEO and Founder of New York Finance Think. He specializes in U.S. banking, financial markets, Federal Reserve policy, investing, corporate earnings, and economic analysis, providing accurate and trustworthy financial news and insights.
Dr. Abhishek Bhatt holds a PhD in history and has studied at top universities worldwide delhi university, Jnu, oxford ,cambrige university , blending deep expertise in geopolitics and global trade. Email: contact@newyorkfinancethink.com
THE NEW GEOPOLITICAL PREMIUM: HOW DE-GLOBALIZATION AND REGULATORY FRAGMENTATION ARE REWIRING ENTERPRISE CAPITAL
By Dr. Abhishek Bhatt | Executive Briefing for New York Finance Think
1. Introduction: The Collision of Statecraft and Balance Sheets
Across the traditional financial corridors of Wall Street and the diplomatic offices of Washington, Tokyo, and London, a historic structural shift is occurring. The traditional separation between international statecraft and domestic monetary execution has vanished. For decades, multinational corporations and Tier-1 financial institutions operated under the assumption of an accelerating, borderless global market characterized by hyper-efficient supply chains and uniform regulatory convergence.
Today, that paradigm has been replaced by a fragmented global landscape where geopolitical alignment dictates capital allocation.
As sovereign nations prioritize industrial security, trade resilience, and technological self-reliance over simple cost optimization, the global financial system is fracturing into distinct regional blocs. For institutional asset allocators, multinational chief executives, and economic policymakers, navigating this macro environment requires a multi-disciplinary framework—one that seamlessly blends historical precedent, macroeconomic metrics, and geopolitical risk modeling.
2. The US-Japan Alliance: Constructing the New Pacific Supply Chain Frontier
The clearest manifestation of this new economic order is the rapidly accelerating strategic partnership between the United States and Japan. Driven by a mutual imperative to de-risk critical supply chains from competing spheres of influence, Washington and Tokyo are actively re-engineering the flow of cross-border corporate investment.
[Geopolitical Tension] ➔ [Sovereign Near-Shoring Mandates] ➔ [Subsidized Capital Injections] ➔ [Higher Baseline Production Costs]
This structural realignment is fundamentally rewriting the playbook for international business operations across the Pacific corridor:
-
- The Semiconductor and Tech Subsidization Wave: Through synchronized legislative mechanisms like the U.S. CHIPS Act and Japan’s targeted technology fundings, billions of dollars in state-backed capital are being funneled into domestic fabrication facilities and secure cross-border joint ventures.
- The Premium on Friend-Shoring: Corporations are moving away from legacy low-cost manufacturing hubs, shifting infrastructure toward politically aligned jurisdictions. While this strategy successfully mitigates the risk of sudden export bans and trade embargoes, it introduces a permanently higher baseline cost of doing business.
3. Monetary Sovereignty and the Fragmentation of Global Central Banking
This geopolitical friction is moving through the plumbing of global central banking. For decades, global liquidity was heavily anchored by the uniform policy directions of major central banks. As international trade routes fragment, individual central banks are increasingly forced to prioritize localized economic defense over international coordination.
+----------------------------+------------------------------------------+------------------------------------------+

| Geopolitical Vector        | Institutional Response                   | Macroeconomic Friction                   |
+----------------------------+------------------------------------------+------------------------------------------+

| Trade Friction & Tariffs   | Localized supply chain duplication       | Persistent structural inflation          |
| Weaponized Liquidity       | Central banks diversify reserve assets   | Fragmentation of global currency velocity|
| Cross-Border Capital Controls| Stricter foreign direct investment reviews| Reduced cross-border M&A deal execution  |
+----------------------------+------------------------------------------+------------------------------------------+
The Reserve Asset Diversification Trend
The strategic use of financial sanctions and asset freezes in recent years has triggered a quiet revolution among sovereign central banks worldwide. Non-aligned nations are systematically reducing their long-term dependencies on Western financial architecture, shifting reserves into hard commodities, physical gold, and localized bilateral clearing networks. This trend is gradually altering the structural velocity of the U.S. dollar in international trade.
The Return of Structural Inflationary Pressures
The duplication of global supply chains, domestic production mandates, and defensive tariff structures mean that the era of secular deflationary forces driven by cheap global labor is over. Central banks must manage monetary policy with the understanding that structural inflation is structurally higher. This reality forces interest rates to remain higher for longer, permanently raising the cost of leverage for corporate expansions.
4. Corporate Earnings in an Age of Fragmented International Business
For large-cap multinational enterprises, the emergence of localized regulatory barriers presents an immediate challenge to corporate earnings and margin sustainability. Operating a global business is no longer just an exercise in logistics; it is an active exercise in regulatory and geopolitical survival.
The Compliance Bureaucracy Premium
Multinational corporations are facing a complex web of contradictory national security regulations, data sovereignty mandates, and foreign direct investment (FDI) restrictions. Navigating these rules requires significant administrative expenditures, hollowing out operational margins and slowing the integration of cross-border mergers and acquisitions.
The Trapped Capital Conundrum
As capital controls tighten globally, multinational firms are finding it increasingly difficult to smoothly repatriate corporate earnings from foreign operations back to their domestic parent entities. This friction locks up valuable capital in local currencies, exposing corporate balance sheets to elevated foreign exchange volatility and reducing the funds available for domestic share buybacks, dividend payouts, or central debt retirement.
5. Looking Ahead: The Executive Framework for the New World Order
As the global financial architecture transitions from a unipolar model to a multi-polar reality, institutional investors and corporate leaders must adjust their long-term valuation models. True corporate resilience is no longer measured solely by quarterly efficiency metrics, but by structural agility and geopolitical alignment.
-
- Auditing Historical Trade Cycles: Sophisticated strategy desks are using deep historical analyses—examining previous eras of intense mercantilism and fragmented trade blocks—to identify which industrial sectors successfully preserve capital during long periods of geopolitical realignment.
- Implementing Geopolitical Risk Premiums: Corporate valuation models are adjusting the discount rates applied to international cash flows. Investments in jurisdictions exposed to maritime trade bottlenecks or political instability are being heavily penalized, while safe-haven corridors are receiving a structural valuation premium.
- Prioritizing Multi-Bilateral Corporate Alliances: Forward-looking enterprises are building flexible, regional operating models. Rather than relying on a centralized global blueprint, they operate as a federation of locally compliant entities, ensuring that an unexpected regulatory flare-up in one region does not destabilize the entire enterprise.
The modern global economy is no longer a purely mathematical machine driven solely by supply and demand curves. It is an intricate extension of historical rivalries, sovereign safety concerns, and strategic resource allocation. Navigating this landscape requires looking past short-term market noise to understand the deeper historical and political currents driving the global movement of capital.
New York Finance Think is a premier research and media institution dedicated to delivering authoritative macroeconomic reporting, sophisticated financial regulation analysis, and actionable geopolitical insights for institutional investors, enterprise executives, and global policymakers.
Dr. Bhatt, as the Chief Executive of New York Finance Think, how would you like our editorial team to expand upon this framework? We can:
-
- Draft a detailed geopolitical analysis focused on the specific capital flows between Wall Street and Japanese technology corridors.
- Develop a proprietary macroeconomic risk model integrating trade fragmentation variables with Federal Reserve policy projections.
- Structure an exclusive executive white paper outlining defensive portfolio strategy recommendations for multinational corporate treasurers.
Let me know your directive for the next research cycle!
Expertise
Specializes in international relations and executive leadership.
Academic Journey
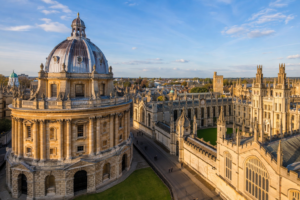 The University of Oxford is one of the world’s oldest and most prestigious universities. It is the oldest university in the English-speaking world, with teaching dating back to at least the late 11th century, and has over nine centuries of continuous academic history.
Our Services
In-depth market analysis, expert banking insights, and global trade updates tailored for you.
Our Team
Faces behind New York Finance Think’s insightful financial coverage.