
Trump Accounts vs. 529 College Savings Plans: What Parents Should Know in 2026
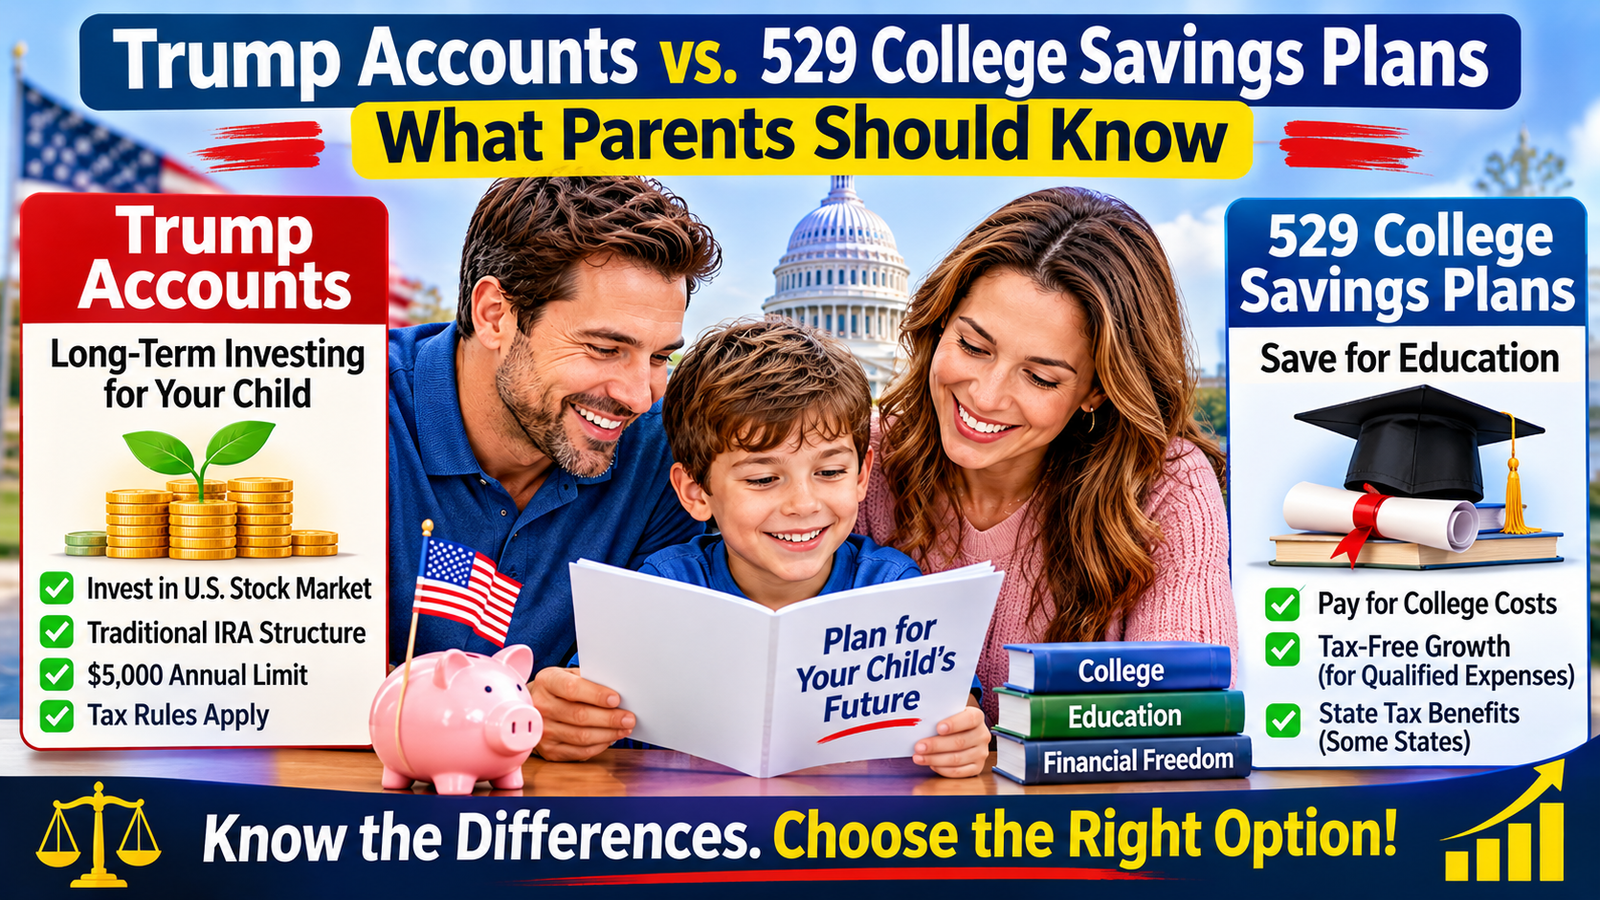
American parents have several ways to prepare financially for their children’s future, but choosing the right savings account is not always easy. College tuition continues to be a major expense for many families, while the cost of housing, transportation, healthcare and everyday living also creates pressure on household budgets. At the same time, a child may need financial support for purposes that go beyond college, including starting a business, buying a first home or building long-term savings.
Two accounts receiving attention in 2026 are Trump Accounts and 529 College Savings Plans. Both are designed to help families build financial resources for children, but they serve different purposes and operate under different tax rules.
A Trump Account is a new type of traditional individual retirement account established for an eligible child. During its growth period, the money is generally invested in eligible low-cost funds tracking broad U.S. equity indexes. A 529 plan, on the other hand, is a tax-advantaged education savings program that allows families to invest money for qualified educational expenses.
The difference is important. A family saving primarily for college may have different priorities from a family that wants to build a long-term investment account for a child. Parents should understand the rules of both accounts before deciding where to contribute.
This guide explains how Trump Accounts and 529 plans work, how their tax benefits differ, what happens when a child does not attend college, how withdrawals are treated, and what families should consider when planning for the future.
1. What Is a Trump Account?
A Trump Account is a new type of child-focused traditional IRA created under federal law. It is established in the child’s name, with a parent or another authorized adult generally acting as the custodian while the child is under 18.
The account is designed to give eligible children an early start in long-term investing. During the account’s growth period, the money must generally remain invested in eligible mutual funds or exchange-traded funds that track qualified indexes, primarily representing U.S. companies.
Unlike a traditional college savings account, a Trump Account is not limited to education expenses. It is designed as a long-term financial account that transitions to traditional IRA rules after the special growth period ends.
The federal government has also established a one-time $1,000 pilot contribution for eligible U.S. citizen children born between January 1, 2025, and December 31, 2028, subject to the applicable election and eligibility rules. This contribution should not be confused with a guaranteed payment for every child.
Parents should also understand that a Trump Account is not a government-guaranteed investment. Its value can rise or fall with the financial markets.
2. What Is a 529 College Savings Plan?
A 529 College Savings Plan is a tax-advantaged savings program established and maintained by a state or eligible educational institution. Families can contribute money to an account for a designated beneficiary, usually a child, and invest it through the plan’s available investment options.
The primary purpose is to help pay qualified education expenses.
These expenses can include eligible college or university tuition, required fees, books, supplies, certain room and board costs, and other expenses recognized under federal tax rules. Federal law also permits certain qualified K–12 education expenses and other education-related uses, subject to applicable limits and requirements.
One of the most important advantages of a 529 plan is its tax treatment. Contributions are made with after-tax money, but investment earnings can grow tax-free at the federal level when withdrawals are used for qualified expenses.
Some states also offer a state income tax deduction or credit for contributions to their own 529 plans. These benefits vary by state, and families should check the rules that apply to their residence.
A 529 plan is therefore closely connected to education planning. It is not designed primarily as a general-purpose investment account.
3. Trump Accounts vs. 529 Plans: The Main Differences
The two accounts have different goals, contribution rules, investment structures and withdrawal restrictions.
Trump Accounts
- Designed for long-term investing for eligible children.
- Structured as a special type of traditional IRA.
- Generally invested in eligible broad U.S. equity index funds during the growth period.
- Contributions during the growth period generally do not qualify for a personal income-tax deduction.
- Withdrawals are generally restricted during the growth period.
- Traditional IRA rules generally apply after the growth period ends.
529 College Savings Plans
- Designed primarily to save for education.
- Operate under state-sponsored or eligible educational institution programs.
- Offer investment portfolios selected by the plan.
- Contributions are not deductible for federal income-tax purposes.
- Some states provide state tax benefits.
- Qualified education withdrawals are generally free from federal income tax.
The most important distinction is the purpose of the money. A 529 plan is designed around education costs. A Trump Account is structured for long-term investment and retirement-related rules.
4. Tax Benefits: How the Two Accounts Differ
Tax treatment can make a major difference to the amount a family eventually receives from an investment account.
With a 529 plan, contributions are generally made using after-tax money. The investment earnings can grow without annual federal income tax, and qualified withdrawals are generally tax-free.
For example, suppose a parent contributes money to a 529 plan over several years. If the investments grow and the child later uses the money for eligible college expenses, the qualified distribution generally does not create federal income tax on the investment earnings.
Trump Accounts operate differently. They are structured as traditional IRAs with special rules during the child’s growth period. Investment earnings can grow tax-deferred, but distributions after the growth period are generally subject to traditional IRA tax rules. The tax treatment depends on the nature of the contributions, the account’s basis and the circumstances of the withdrawal.
This means parents should not assume that money withdrawn from a Trump Account will receive the same tax-free treatment as a qualified 529 distribution.
A further distinction is that some states offer tax incentives for 529 contributions. A family should check whether its state provides a deduction or credit and whether the benefit depends on using the state’s own plan.
5. Where Is the Money Invested?
Investment choices are another major difference.
During the growth period, Trump Account assets are generally restricted to eligible mutual funds and ETFs tracking qualified indexes. These investments must meet requirements including no leverage and an annual fund expense limit of 0.1% of the investment balance.
The intention is to provide exposure to broad U.S. equity markets rather than allowing unrestricted investment in individual stocks or speculative products.
A 529 plan usually offers a different selection of investment portfolios. Depending on the state plan, families may find age-based portfolios, target-enrollment portfolios, stock and bond combinations, and other investment choices.
Age-based portfolios generally become more conservative as the beneficiary approaches college age. This approach is intended to reduce the risk of a major market decline shortly before the money is needed.
Neither investment structure eliminates market risk. Stock funds can decline, bond funds can lose value, and past performance does not guarantee future returns.
Parents should examine investment fees, diversification, risk levels and the time remaining before the money is needed.
6. What Happens If a Child Does Not Attend College?
This is one of the most important questions for parents.
A 529 plan is designed for qualified education expenses, but a child who does not attend a traditional four-year college does not automatically lose the money.
The funds may still be used for other eligible educational purposes, including certain vocational and technical programs, eligible apprenticeship programs and other qualified expenses. The beneficiary can also be changed to another eligible family member under applicable rules.
In addition, federal law allows certain 529 funds to be rolled over to the beneficiary’s Roth IRA, subject to strict conditions. These include a 15-year account-age requirement, a $35,000 lifetime rollover limit, annual Roth IRA contribution limits and restrictions involving recent contributions and earnings. This is not an unrestricted way to move an entire 529 balance into a Roth IRA.
If money is withdrawn for a nonqualified purpose, the earnings portion is generally subject to income tax and an additional 10% federal tax, although exceptions may apply.
Trump Accounts are not restricted to college expenses in the same way. However, the account is not a regular savings account that parents can freely withdraw from whenever they choose. Distributions are generally restricted during the growth period, and traditional IRA rules apply after that period.
The account holder may face income tax and potentially an early-distribution penalty depending on the reason for the withdrawal and whether an exception applies.
7. Can Parents Use Both Accounts?
Families do not necessarily have to choose only one.
A parent may consider using a 529 plan for anticipated education expenses while treating a Trump Account as a separate long-term investment account.
For example, a family could contribute regularly to a 529 plan to prepare for future tuition and education costs. Separately, the family could establish or fund an eligible child’s Trump Account under the applicable rules.
This approach recognizes that children may have several financial needs as they grow older. College is one possibility, but it is not the only expense a young adult may face.
However, families should first review their household budget. Contributing to multiple accounts should not come at the expense of emergency savings, high-interest debt repayment or essential household expenses.
8. Contribution Limits and Funding Rules
Trump Accounts generally have a $5,000 annual contribution limit during the growth period, subject to inflation adjustments and statutory exceptions. Certain qualified government or nonprofit contributions facilitated through the Treasury Department are treated differently under the rules. The $1,000 pilot contribution for eligible children also does not count toward the ordinary annual limit.
Certain employer contributions may receive special tax treatment, subject to the applicable statutory limit and rules.
529 plans operate differently. Federal tax law does not establish one universal annual contribution limit in the same way as a Trump Account. However, contributions are subject to gift-tax rules, and each plan may have an overall account balance limit based on expected education costs.
Large contributions may qualify for special gift-tax treatment through the five-year election, but this requires careful tax planning.
Parents should check the specific 529 plan’s rules and consult a tax professional before making unusually large contributions.
9. Who Controls the Account?
Control is another important consideration.
A Trump Account is established for the child, with an authorized adult serving as custodian during the child’s minority. The account is subject to special rules until the growth period ends. Afterward, traditional IRA rules generally apply.
With a 529 plan, the account owner usually retains significant control over the account. The owner can generally choose investments from the plan’s available options, request qualified distributions and change the beneficiary to another eligible family member.
This difference matters because a 529 account is generally controlled by the account owner, while a Trump Account is legally established for the child and follows IRA-related rules.
Parents should read the account documents carefully to understand who can make investment decisions, request distributions and manage the account.
10. What If the Child Receives a Scholarship?
Scholarships are common, and families should understand how they affect education savings.
If a student receives a scholarship, the family may need less money from a 529 plan. However, a scholarship does not automatically make the remaining 529 funds unusable.
Under federal rules, a distribution up to the amount of certain scholarships may qualify for an exception to the additional 10% tax on nonqualified distributions. The earnings portion may still be subject to ordinary income tax.
Other options may include keeping the money invested for future qualified education expenses, changing the beneficiary to an eligible family member or considering a qualifying Roth IRA rollover if all requirements are met.
A Trump Account is not specifically tied to scholarship eligibility. Its distribution restrictions and tax rules continue to apply independently.
11. What Should Parents Consider Before Opening a 529 Plan?
Parents should compare plans rather than selecting one only because it is offered by their state.
Important considerations include:
- State income-tax deductions or credits.
- Investment options and diversification.
- Administrative and fund expenses.
- Account minimums and contribution requirements.
- Age-based portfolio options.
- Rules for changing beneficiaries.
- Qualified education expenses.
- The plan’s website, customer service and account management tools.
A low-cost plan with investment choices that match the family’s time horizon may be worth considering. However, the value of a state tax benefit can also be significant.
12. What Should Parents Consider Before Funding a Trump Account?
Parents should understand the account’s long-term structure before contributing.
They should review eligibility, the pilot contribution requirements, the annual contribution limit, investment restrictions, fees and the rules that apply when the child reaches adulthood.
They should also remember that broad stock-market exposure can involve substantial volatility. A market decline can reduce the account balance, particularly over shorter periods.
A Trump Account should not be treated as a guaranteed source of college funding or as a substitute for an emergency savings account.
13. A Simple Example: Two Different Financial Goals
Imagine a family with a newborn child. The parents want to prepare for college, but they also want the child to have a financial foundation in adulthood.
They could use a 529 plan to build a dedicated education fund. Contributions could be invested in an age-based portfolio, and qualified education withdrawals could receive federal tax-free treatment.
At the same time, the family could consider a Trump Account as a separate long-term investment arrangement. The account’s eligible investments would provide exposure to broad U.S. equity markets during the growth period, subject to the applicable rules.
The two accounts would serve different purposes. The 529 plan would focus on education, while the Trump Account would follow its own long-term investment and IRA framework.
The outcome would depend on contribution amounts, investment performance, fees, tax rules and the family’s future needs. No account can guarantee a particular balance.
14. Common Mistakes Parents Should Avoid
Mistake 1: Assuming both accounts are tax-free in the same way.
A qualified 529 withdrawal generally receives tax-free treatment. Trump Account distributions follow traditional IRA tax rules after the growth period. These are not identical tax benefits.
Mistake 2: Assuming a Trump Account is a college savings account.
It is not specifically designed for college expenses. It is a child-focused traditional IRA with special rules.
Mistake 3: Assuming every child automatically receives $1,000.
The pilot contribution has specific citizenship, birth-year and election requirements.
Mistake 4: Ignoring investment risk.
Both accounts involve investments that can lose value. A long time horizon may help investors manage volatility, but it does not remove market risk.
Mistake 5: Ignoring fees and state tax benefits.
Investment expenses and state-specific tax incentives can influence the overall value of an account.
Mistake 6: Contributing more than the family budget allows.
Parents should maintain financial stability and avoid taking on high-interest debt just to fund a child’s investment account.
15. Frequently Asked Questions
Are Trump Accounts and 529 plans the same?
No. Trump Accounts are a type of traditional IRA with special rules for eligible children. 529 plans are tax-advantaged accounts designed primarily for qualified education expenses.
Can a child have both a Trump Account and a 529 plan?
Yes. The accounts serve different purposes and can be considered separately, subject to each account’s eligibility and contribution rules.
Which account is designed specifically for college?
A 529 plan is specifically designed to help pay qualified education expenses. Trump Accounts are structured for long-term investing and follow IRA-related rules.
Are 529 plan withdrawals tax-free?
Qualified 529 withdrawals are generally free from federal income tax when used for eligible expenses. Nonqualified withdrawals may result in income tax and an additional 10% tax on the earnings portion, subject to exceptions.
Does a Trump Account guarantee investment growth?
No. Trump Accounts invest in eligible market-based funds, and the value can rise or fall. There is no guaranteed investment return.
Can 529 money be transferred to a Roth IRA?
Certain 529 funds can be transferred to the beneficiary’s Roth IRA if strict conditions are met. These include the 15-year account requirement, annual contribution limits and a $35,000 lifetime rollover cap.
Can parents withdraw Trump Account money before the child turns 18?
Generally, distributions are restricted during the growth period, subject to limited exceptions and permitted rollovers. Parents should check the current IRS rules before attempting a withdrawal.
Conclusion: Understand the Purpose Before Choosing an Account
Trump Accounts and 529 College Savings Plans are not interchangeable products. They were created with different financial goals and different tax rules.
A 529 plan is designed to help families prepare for education expenses, with tax-free growth and qualified withdrawals. A Trump Account is structured as a long-term investment account for eligible children, with special contribution and investment rules during the growth period and traditional IRA rules afterward.
For parents, the important decision is not simply which account has the larger potential balance. It is understanding what the money is intended to accomplish, when it may be needed, how much investment risk the family can accept and what tax rules will apply.
Some families may find that a 529 plan fits their education savings goals. Others may consider a Trump Account as an additional long-term investment arrangement. Families with the financial capacity may consider both, while maintaining a sensible household budget.
Before making a decision, review the official IRS guidance, the rules of the relevant 529 plan and the account documents. Tax rules can change, and individual circumstances matter.
Disclaimer: This article is for educational and informational purposes only. It is not tax, legal or investment advice. Parents should consult a qualified tax or financial professional about their individual circumstances.
Sources and References
- Internal Revenue Service (IRS) – Trump Accounts FAQs
- U.S. Securities and Exchange Commission – Investor.gov
- Internal Revenue Service – Qualified Tuition Programs (529 Plans)
- IRS Publication 970 – Tax Benefits for Education
- U.S. Department of the Treasury – Trump Accounts
- Congressional Research Service – Trump Accounts: Overview and Policy Considerations
Sources accessed October 31, 2026. Readers should verify current federal and state tax rules before making financial decisions.
