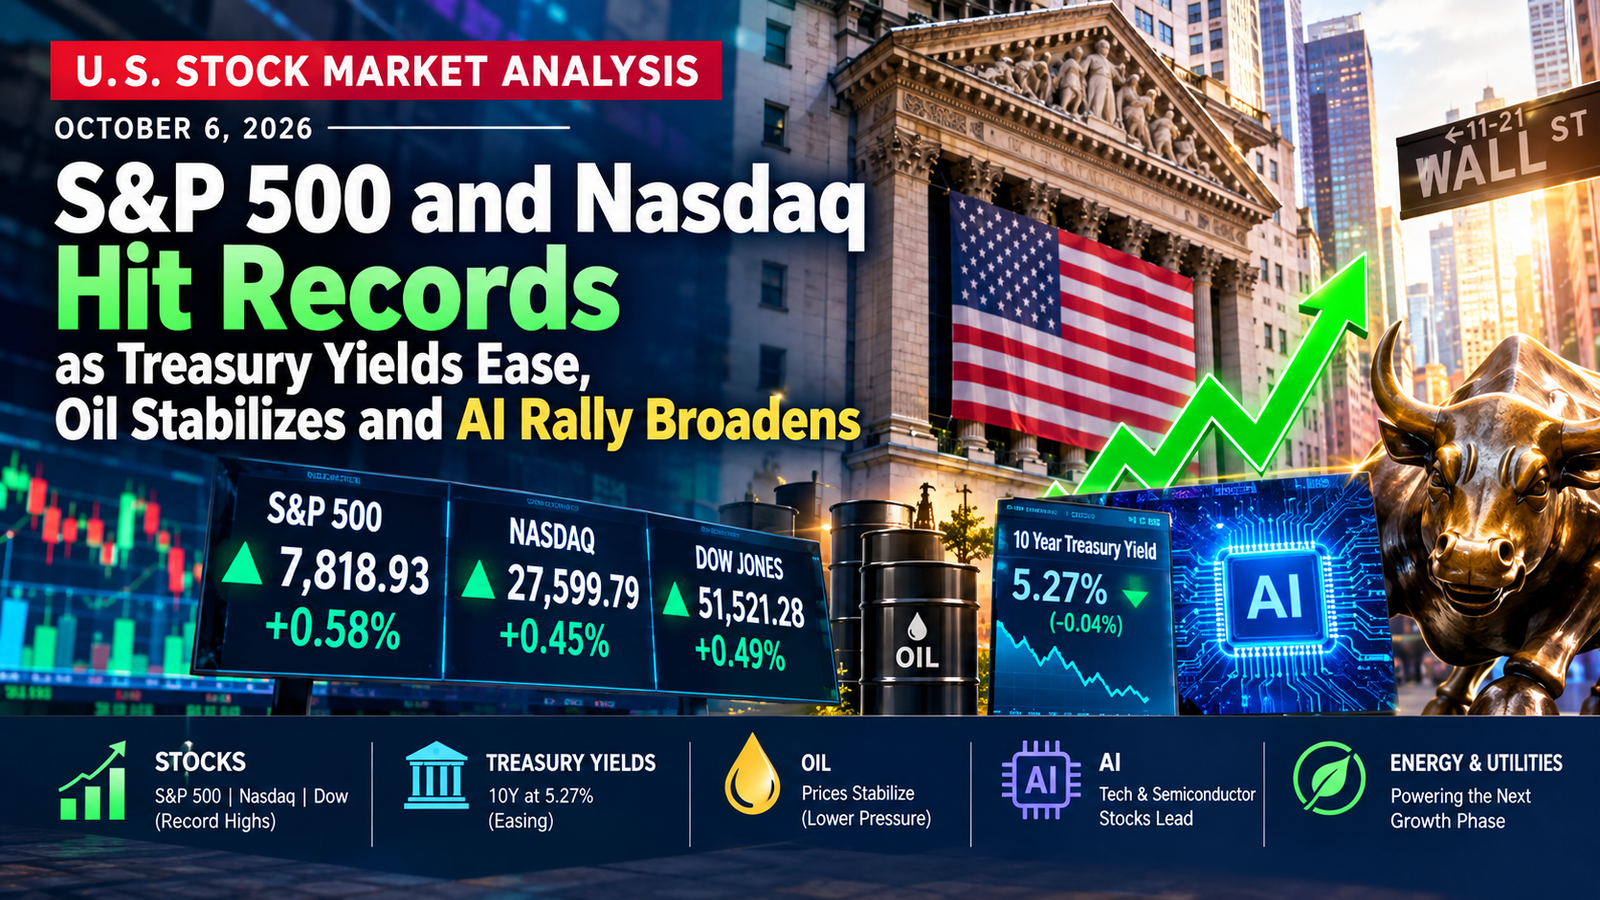
How Interest Rates, Inflation, and Treasury Yields Affect Stocks and Your Household Budget
When you fill up your gas tank, buy groceries, pay your mortgage, or check your retirement account, you might not immediately connect those expenses to the bond market or Federal Reserve. Yet these financial forces are closely connected.
Interest rates influence how much it costs to borrow money. Inflation determines how quickly everyday expenses rise. Treasury yields help shape borrowing costs across the economy and influence how investors value stocks. Together, these factors can affect everything from the monthly payment on a new car to the long-term performance of a 401(k).
For American households, understanding these relationships can make economic headlines easier to interpret and financial decisions less confusing.
In this guide, we will explain how interest rates, inflation, and U.S. Treasury yields work, why they matter to the stock market, and what they can mean for your household budget.
What Are Interest Rates, Inflation, and Treasury Yields?
These three terms often appear together in financial news, but each describes something different.
What Are Interest Rates?
An interest rate is the cost of borrowing money or the return earned for lending or depositing it. When you take out a mortgage, use a credit card, finance a car, or maintain a savings account, interest rates can affect your finances.
The Federal Reserve, America’s central bank, sets a target range for the federal funds rate. This is the rate banks charge one another for certain overnight loans. Although it is not the same as the interest rate on your mortgage or credit card, changes in the federal funds rate can influence many other rates throughout the economy.
When the Fed raises rates, borrowing generally becomes more expensive. When it lowers rates, some forms of borrowing may become less expensive. The timing and size of these changes depend on financial markets, lenders, and broader economic conditions. Federal Reserve
What Is Inflation?
Inflation is a broad increase in the prices of goods and services over time. It affects how much your money can buy.
Consider a household that spends $200 a week on groceries. If the overall cost of its usual grocery basket rises by 5%, that basket would cost about $210, assuming the household buys the same items and quantities.
The difference may seem small at first. Over a year, however, higher grocery bills, insurance premiums, utilities, housing costs, and transportation expenses can put significant pressure on a household budget.
In the United States, the Bureau of Labor Statistics publishes the Consumer Price Index (CPI), a widely followed measure of changes in consumer prices. The Federal Reserve also pays close attention to inflation measures based on the Personal Consumption Expenditures (PCE) price index.
Importantly, lower inflation does not necessarily mean prices are falling. If inflation slows from 5% to 3%, prices are generally still rising, just more slowly.
What Are U.S. Treasury Yields?
U.S. Treasury securities are debt instruments issued by the federal government. They include Treasury bills, notes, and bonds with different maturities.
A Treasury yield represents the return investors receive based on a security’s price and its payment terms. Market yields change as investors buy and sell Treasury securities.
Two yields often receive particular attention:
- The 2-year Treasury yield: Often reflects expectations about near-term interest rates and monetary policy.
- The 10-year Treasury yield: Influenced by expectations for future interest rates, inflation, economic growth, and the compensation investors require for holding longer-term debt.
These are useful indicators, not perfect forecasts. Treasury yields can move for several reasons, even when the Federal Reserve has not changed its policy rate.
You can find official U.S. Treasury yield data through the U.S. Department of the Treasury.
How Interest Rates Affect the Stock Market
Interest rates are an important part of stock market valuation. They influence company borrowing costs, consumer spending, and the returns investors can earn from other assets.
However, rising interest rates do not automatically cause stocks to fall, and rate cuts do not guarantee a stock market rally.
1. Higher Borrowing Costs Can Reduce Corporate Profits
Companies often borrow money to expand operations, purchase equipment, hire employees, or develop new products.
When interest rates rise, businesses that rely on borrowing may face higher financing expenses. If revenue does not grow enough to offset those costs, profits can suffer.
Imagine a company planning to borrow money to build a new manufacturing facility. If its financing becomes more expensive, management may delay the project, reduce its size, or decide that the expected return is no longer attractive.
Investors may respond by lowering their expectations for future earnings, which can put pressure on the company’s stock price.
The effect varies by business. A company with substantial cash reserves and little debt may be less affected than a highly leveraged company that frequently refinances its borrowing.
2. Higher Rates Can Change Stock Valuations
Investors do not value stocks only by looking at current profits. They also consider the cash a company might generate in the future.
When market interest rates rise, future earnings may become less valuable in today’s dollars under common valuation methods. Investors may also have more opportunities to earn income from Treasury securities or other interest-bearing assets.
This can make some stocks less attractive at their previous prices.
Growth-oriented companies can be particularly sensitive because a significant portion of their expected value may depend on earnings far into the future. This is one reason interest rate expectations often influence technology stocks and the Nasdaq-100.
Still, company earnings, innovation, competitive advantages, and investor expectations also matter. Interest rates are only one part of the picture.
3. Lower Rates May Support Stocks
When the Federal Reserve lowers its policy rate, borrowing costs may eventually ease across parts of the economy. Businesses may find it easier to finance expansion, and consumers may find certain loans more affordable.
Lower rates can also make future corporate earnings more attractive in valuation models.
These conditions may support stock prices, particularly if economic growth remains healthy.
But there is an important qualification: the Fed sometimes cuts rates because the economy is weakening. If falling rates coincide with rising unemployment, declining corporate profits, or recession concerns, stocks can still fall.
The reason behind a rate change can matter as much as the change itself.
How Inflation Affects Stocks and Investments
Inflation influences both the costs businesses face and the purchasing power of consumers. Its effect on stocks depends on how quickly prices rise, whether companies can pass higher costs on to customers, and how policymakers respond.
Higher Costs Can Squeeze Profit Margins
Businesses pay for labor, materials, transportation, energy, rent, and other operating expenses. When these costs rise faster than sales revenue, profit margins can shrink.
For example, a restaurant may face higher food prices, wages, and utility bills. It might raise menu prices to compensate, but customers may cut back if meals become too expensive.
A business that cannot pass its higher costs on to customers may experience slower profit growth.
Companies with strong brands, pricing power, or efficient operations may handle inflation better than those operating with thin margins. Even so, no company is completely insulated from economic pressures.
Inflation Can Lead to Higher Interest Rates
If inflation remains persistently elevated, the Federal Reserve may keep monetary policy restrictive or raise its policy rate to help bring inflation under control.
Higher borrowing costs can slow consumer spending and business investment. Over time, weaker demand may reduce pressure on prices.
This process does not happen immediately. Monetary policy affects the economy with delays, and supply disruptions, energy prices, housing costs, and other factors can complicate the outlook.
For stock investors, unexpectedly high inflation can create uncertainty about future interest rates, earnings, and valuations.
Inflation Reduces Purchasing Power
Inflation can affect households even when their income increases.
Suppose your annual salary rises by 3%, but the prices of the goods and services you regularly purchase rise by 4%. Your income has increased in dollar terms, but your purchasing power has declined if your spending pattern remains similar.
This is why it is important to distinguish between nominal returns and real returns.
A nominal investment return measures the percentage increase in the investment’s dollar value. A real return adjusts for inflation and provides a better indication of how purchasing power has changed.
For example, if an investment earns 7% over a year and inflation is 3%, its real return is approximately 3.9%, before taxes and fees, assuming those rates apply to the same period.
Why Treasury Yields Matter to Stock Investors
Treasury yields receive considerable attention because U.S. government securities are widely used as reference points for pricing other financial assets.
Changes in Treasury yields can influence mortgage rates, corporate borrowing costs, bond prices, and stock valuations.
Treasury Yields and the S&P 500
The S&P 500 tracks approximately 500 leading publicly traded U.S. companies and is widely used as a benchmark for the large-cap U.S. stock market.
When Treasury yields rise, investors may reassess how much they are willing to pay for the future earnings of S&P 500 companies.
For example, if investors can earn a higher yield from relatively low-credit-risk Treasury securities, they may demand a greater potential return before buying stocks. This can put downward pressure on stock valuations.
However, the relationship is not automatic. If Treasury yields rise because economic growth is stronger than expected, corporate earnings may also improve. In that situation, stocks may rise despite higher yields.
The reason yields are moving matters.
What Happens When Treasury Yields Rise?
Rising Treasury yields can have several effects:
- Stock valuations: Higher yields may put pressure on the prices investors are willing to pay for future earnings.
- Corporate financing: Companies may face higher costs when issuing new debt or refinancing existing debt.
- Mortgage rates: Long-term Treasury yields can influence mortgage pricing, although mortgage rates also reflect other factors.
- Savings and fixed income: Newly issued bonds and some savings products may offer more attractive yields.
- Existing bonds: The market prices of existing fixed-rate bonds generally fall when comparable market yields rise.
The last point is particularly important for investors who hold bond funds or individual bonds and may need to sell before maturity.
What Happens When Treasury Yields Fall?
Falling yields can ease financial pressure in some circumstances. Mortgage rates and corporate borrowing costs may decline, and lower discount rates may support stock valuations.
But falling yields can also signal that investors expect slower economic growth or weaker demand.
If yields decline because markets anticipate a recession, stock prices may remain under pressure even as borrowing conditions begin to improve.
For that reason, investors should consider Treasury yields alongside economic growth, inflation, employment, and corporate earnings rather than interpreting one indicator in isolation.
How Interest Rates and Inflation Affect Your Household Budget
Financial market changes are not limited to Wall Street. They can affect everyday expenses, monthly payments, savings, and long-term financial goals.
1. Mortgage Rates and Home Affordability
For many American households, buying a home is one of the largest financial commitments they will make.
Mortgage rates are influenced by several factors, including longer-term Treasury yields, mortgage-backed securities markets, lender costs, and expectations for future inflation.
When mortgage rates rise, a homebuyer may qualify for a smaller loan or face a higher monthly payment on the same purchase price.
Consider a hypothetical 30-year fixed-rate mortgage of $350,000:
- At a 6% annual interest rate, principal and interest are approximately $2,098 per month.
- At a 7% annual interest rate, principal and interest are approximately $2,329 per month.
That is a difference of about $231 per month, or roughly $2,772 per year.
These estimates exclude property taxes, homeowners insurance, mortgage insurance, and other housing expenses. They illustrate how a seemingly modest change in mortgage rates can affect affordability.
Homeowners with existing fixed-rate mortgages generally keep the same contractual principal-and-interest payment. Those with adjustable-rate mortgages may face changes when their loans reset, depending on their loan terms.
2. Credit Cards and Personal Loans
Many credit cards have variable interest rates. When the rates used by lenders rise, the cost of carrying a credit card balance may increase.
For households already managing high balances, additional interest can make it harder to pay down debt.
Personal loans and some other forms of consumer borrowing can also become more expensive when lending conditions tighten.
A practical step is to review the interest rates on outstanding debts, understand how payments are calculated, and prioritize a repayment strategy that fits your circumstances. Paying down high-interest debt can reduce future interest expenses, although households should also account for essential bills and emergency savings.
3. Auto Loans and Transportation Costs
Interest rates affect the financing cost of buying a new or used vehicle.
A higher auto loan rate can increase the monthly payment even if the vehicle price remains unchanged. Buyers may respond by choosing a less expensive car, making a larger down payment, or extending the loan term.
However, a longer loan term can increase total interest costs and leave borrowers owing more than their vehicle is worth for longer.
Inflation can add another layer of pressure through fuel, maintenance, insurance, and repair expenses.
When comparing vehicles, it helps to look beyond the advertised monthly payment and calculate the total cost of ownership.
4. Groceries, Utilities, and Everyday Expenses
Inflation affects the prices households pay for food, electricity, natural gas, transportation, medical care, and other goods and services.
Not every category rises at the same pace. Gasoline prices can change quickly, while housing-related expenses or insurance premiums may adjust more gradually.
This means the inflation rate reported nationally may not match the experience of an individual family.
A household that spends a large share of its income on rent, food, and transportation may feel price increases more strongly than a household with different spending patterns.
Tracking expenses over several months can help identify where costs are rising most quickly and where adjustments may be possible.
5. Savings Accounts and Certificates of Deposit
Higher interest rates can benefit savers by increasing the yields available on certain savings accounts and certificates of deposit (CDs).
For example, a savings account paying a higher annual percentage yield (APY) can generate more interest than an otherwise comparable account paying a lower APY.
However, the return should be considered alongside inflation.
If a savings account earns 3% and inflation is 4%, the purchasing power of the balance declines by approximately 1% in real terms over the year, before taxes and assuming those rates apply for the same period.
Rates vary by financial institution and product. Some accounts adjust their yields as market conditions change, while CDs may lock in a rate for a specified period and impose penalties for early withdrawal.
6. Retirement Accounts and 401(k) Plans
Interest rates, inflation, and Treasury yields can also affect retirement savings.
A 401(k) invested in stock funds may experience market volatility when investors reassess corporate earnings and valuations. Bond funds can fluctuate when market yields change.
At the same time, inflation can reduce the future purchasing power of retirement savings.
This does not mean investors should automatically change their retirement strategy whenever interest rates move. Retirement planning generally involves a longer time horizon, and frequent reactions to economic headlines can introduce additional risks.
A diversified portfolio aligned with your time horizon, risk tolerance, and financial needs can help you manage different market environments. The appropriate mix of investments varies by individual.
A Simple Example: How One Economic Change Can Affect a Family
Imagine a household planning to purchase a home while also contributing to a retirement account.
Inflation pushes up grocery and insurance expenses, leaving less room in the monthly budget. At the same time, Treasury yields rise, and mortgage lenders increase the rates they offer to new borrowers.
The family now faces two pressures: everyday costs have increased, and financing a home has become more expensive.
Meanwhile, higher market yields may put pressure on some stock valuations, potentially affecting the value of the family’s retirement investments.
This example does not mean every asset or household will respond in the same way. A saver may earn more interest, a homeowner with a fixed-rate mortgage may see no change in the principal-and-interest payment, and a company with strong earnings may continue to perform well.
The broader lesson is that the same economic environment can create both challenges and opportunities, depending on a household’s debt, income, savings, and investments.
What Should Americans Watch in Economic News?
You do not need to follow every financial headline to understand the forces affecting your money. A few indicators provide a useful starting point.
Consumer Price Index (CPI): Published by the U.S. Bureau of Labor Statistics, CPI measures changes in prices paid by consumers. Look at both the overall index and core CPI, which excludes food and energy.
Personal Consumption Expenditures (PCE) price index: This inflation measure is closely watched by the Federal Reserve when assessing price trends.
Federal Reserve announcements: Policy statements and economic projections can help explain the Fed’s view of inflation, employment, and interest rates.
2-year and 10-year Treasury yields: These market rates can offer clues about changing expectations for interest rates, inflation, and economic growth.
Employment and wage growth: Jobs and earnings influence household purchasing power and consumer demand.
Corporate earnings: Company revenue, profit margins, and management outlooks help investors evaluate whether businesses can adapt to changing economic conditions.
Use these indicators together. A single report rarely provides enough information to explain the entire stock market or predict its next move.
Practical Ways to Prepare for Changing Rates and Inflation
No household can control inflation, Treasury yields, or Federal Reserve decisions. But families can take practical steps to improve their financial resilience.
- Review your monthly budget. Identify essential expenses, discretionary spending, debt payments, and opportunities to build savings.
- Understand your debt. Check whether your loans have fixed or variable rates, when any introductory rates expire, and what refinancing would actually cost.
- Build emergency savings. A cash reserve can help cover unexpected bills without relying immediately on expensive borrowing.
- Compare savings products. Review APYs, fees, withdrawal restrictions, and deposit insurance coverage rather than choosing an account based only on its advertised rate.
- Keep investment decisions aligned with your goals. Avoid changing a long-term investment strategy solely because of a short-term market reaction.
- Diversify thoughtfully. Stocks, bonds, and cash serve different purposes, and each has its own risks.
- Review major purchases carefully. When financing a home or vehicle, compare total borrowing costs and monthly payments under different interest-rate scenarios.
These steps cannot eliminate financial risk, but they can help households make more informed decisions when economic conditions change.
Frequently Asked Questions
Do higher interest rates always cause the stock market to fall?
No. Higher rates can put pressure on stock valuations and borrowing costs, but stocks may still rise if economic growth and corporate earnings are strong. Market reactions also depend on whether the rate change was expected.
Why do Treasury yields affect mortgage rates?
Mortgage rates are influenced by longer-term borrowing costs in financial markets. Treasury yields provide an important benchmark, but mortgage rates also reflect mortgage-backed securities pricing, lender costs, and other factors.
Can inflation be high even when the economy is growing?
Yes. Strong demand can contribute to inflation, but prices can also rise because of supply disruptions, higher energy costs, or other factors. Economic growth and inflation do not always move in the same direction.
Are Treasury bonds a risk-free investment?
U.S. Treasury securities are generally considered to have very low credit risk because they are backed by the U.S. government. However, they are not free of all investment risks. Selling a bond before maturity can result in a loss, and inflation can reduce the purchasing power of its returns.
Should I stop investing when interest rates rise?
Not necessarily. The appropriate investment approach depends on your goals, time horizon, financial situation, and risk tolerance. Higher rates can affect different investments in different ways. A long-term plan should account for uncertainty rather than rely on one economic indicator.
What is the difference between inflation and the cost of living?
Inflation measures how prices change over time across a defined basket of goods and services. The cost of living describes the expenses associated with maintaining a particular lifestyle in a particular place. Individual households may experience different cost increases because their spending patterns differ.
Final Thoughts
Interest rates, inflation, and Treasury yields may seem like topics reserved for economists and Wall Street analysts, but they have direct consequences for everyday Americans.
Interest rates influence borrowing costs and savings returns. Inflation affects the purchasing power of income. Treasury yields help shape conditions in the bond market, mortgage market, and stock market.
Together, these forces can influence home affordability, credit card interest, business profits, retirement accounts, and household budgets.
The most useful approach is to understand how the pieces fit together without assuming that every rate increase is bad for stocks or every rate cut is good. Economic conditions are complex, and the reasons behind a change often matter more than the headline itself.
By following reliable economic data, reviewing household finances, and maintaining a plan suited to your needs, you can make more informed decisions even when financial markets are uncertain.
Disclaimer: This article is for educational purposes only and is not individualized financial, investment, tax, or mortgage advice. Investment values can rise or fall, and borrowing terms vary by lender and borrower.